A few large transactions drove cardiovascular dealmaking in Q3 2026. Partnership and M&A deal counts fell from Q2, while venture and IPO capital rose.
R&D partnerships fell 60% to 2 from 5, while value rose to $2.0B from $1.1B. One deal provided the entire $70M upfront, up 32% from $53M. Deals to know: Atavistik Bio and Roche, $70M upfront and up to $1.9B in milestones for small-molecule cardiovascular, renal, and metabolic therapies; CellProthera and Alfresa Holdings, terms not disclosed, Japan rights to ProtheraCytes, a Phase 2 stem-cell therapy for severe heart attack.
M&A deals fell 54% to 6 from 13. Value including contingent payments fell 27% to $6.0B from $8.2B, while cash value rose 23% to $5.9B from $4.8B. Average and median upfronts both reached $3.0B, from $796M and $918M, respectively. Deals to know: KKR acquiring Integer Holdings, $127 per share, a 4.78% premium, for a $5.7B enterprise value, a medical device contract manufacturer take-private; Medtronic option to acquire Pi-Cardia, up to an estimated $210M upfront plus earn-outs and up to $80M invested, ShortCut heart valve device maker.
Venture funding rounds edged up 4% to 24 from 23, while capital more than doubled to $1.7B from $726M. Deals to know: Neko Health’s $700M series C, health scans for stroke and heart attack risk; Function Health’s $450M growth financing from General Catalyst’s Customer Value Fund, lab testing and imaging.
IPOs rose 200% to 3 from 1, and proceeds grew 31% to $602M from $460M. Deals to know: Braveheart Bio’s $440M offering, Phase 3 cardiac myosin inhibitor BHB-1893 for hypertrophic cardiomyopathy; Scribe Therapeutics’ offering of about $148M, plus a $8M Sanofi private placement, Phase 1 PCSK9-silencing therapy STX-1150 for LDL cholesterol.
Cardiovascular R&D Partnerships
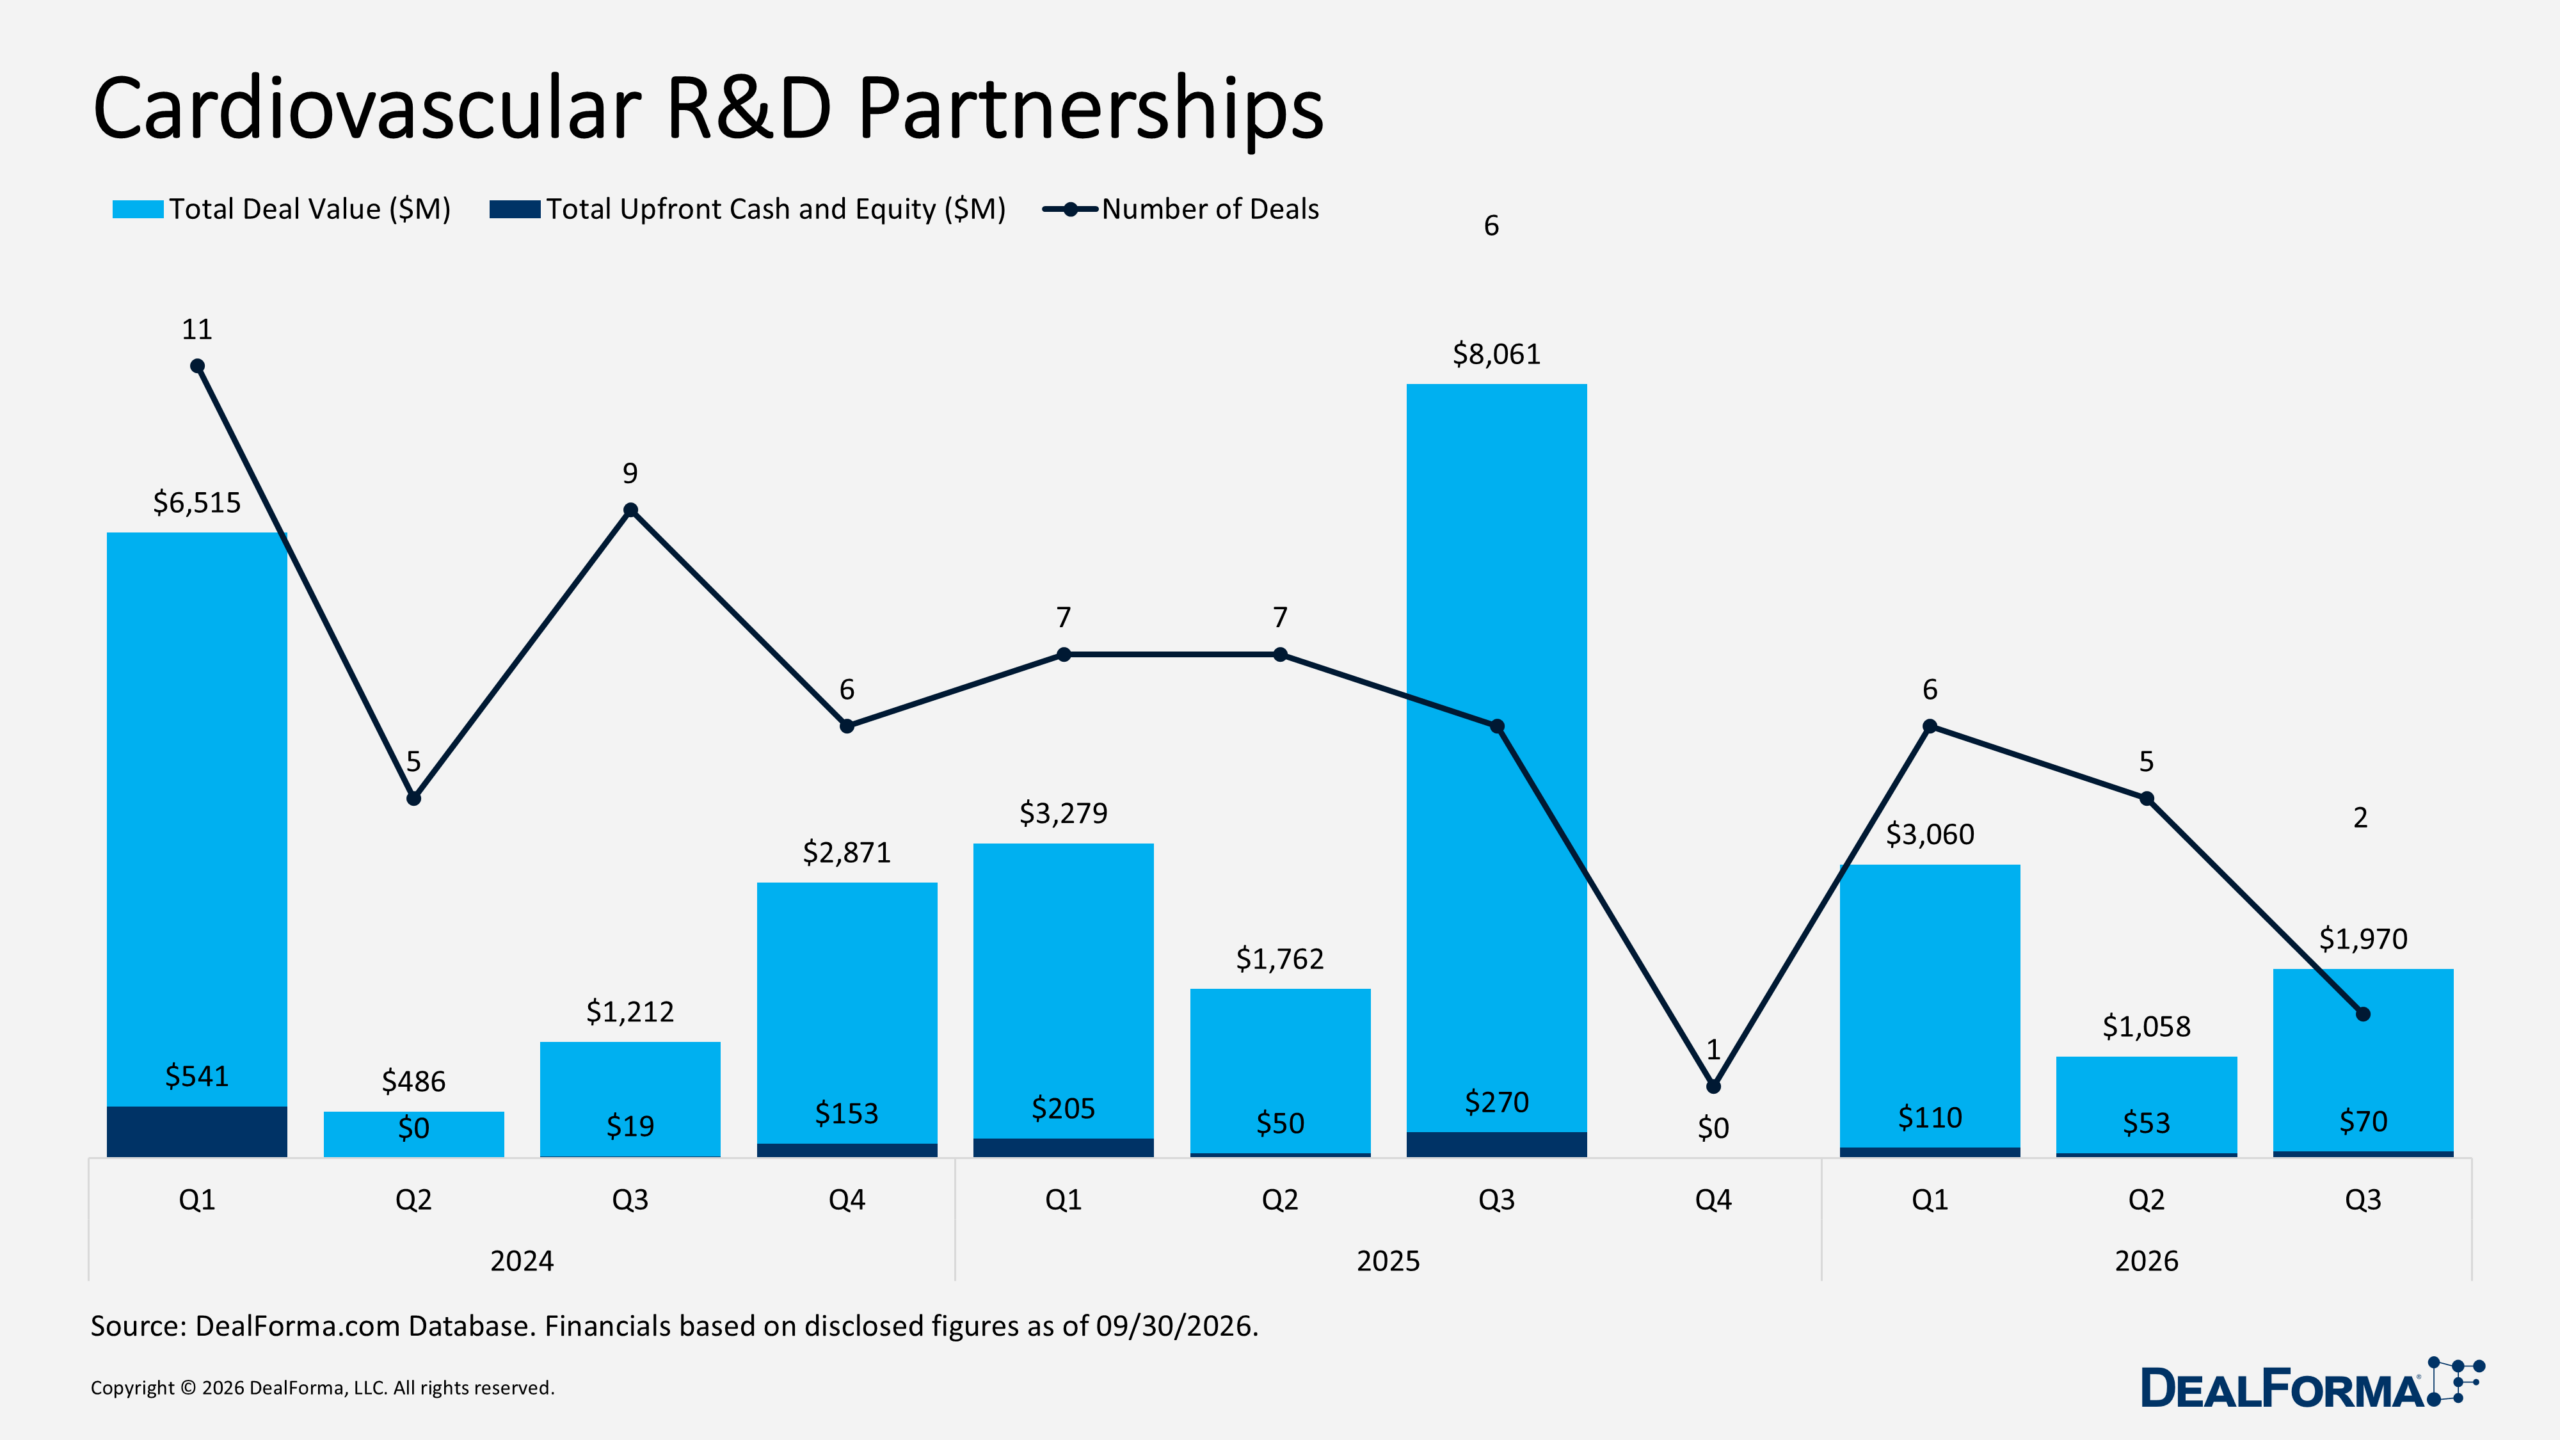
Cardiovascular R&D partnership activity became more concentrated in Q3 2026. Deal volume fell 60% quarter over quarter, to 2 deals from 5 in Q2. Total deal value, however, jumped 86% to $2.0B from $1.1B, showing that fewer but significantly larger transactions drove the quarter. Total upfront cash and equity also rose 32% to $70M from $53M. Average and median upfront payments each increased 169% to $70M from $26M. Combined, Q2 and Q3 2026 produced 7 deals totaling $3.0B in value and $123M in upfront cash and equity.
Prominent Cardiovascular R&D Partnerships in Q3 2026
Atavistik Bio development and commercialization deal with Roche – September 2026
Roche will pay Atavistik Bio $70M upfront and up to $1.9B in research, development, and commercial milestones (breakouts not disclosed). Tiered royalties on future net sales also apply. In return, Roche gains rights to discover, develop, and commercialize allosteric small-molecule therapies for cardiovascular, renal, and metabolic (CVRM) diseases. Atavistik’s AMPS platform and allosteric discovery capabilities will identify functional binding pockets against multiple targets. Atavistik handles discovery and research; Roche takes on preclinical, clinical development, regulatory, and commercialization activities.
CellProthera development and commercialization deal with Alfresa Holdings – August 2026
CellProthera granted Alfresa Holdings exclusive rights in Japan to develop, distribute, and commercialize ProtheraCytes. The Phase 2 asset is an autologous CD34+ stem-cell therapy for severe myocardial infarction. Both companies intend to negotiate an agreement covering the conduct and financing of a Phase 3 trial. Financial terms were not disclosed.
Cardiovascular M&A
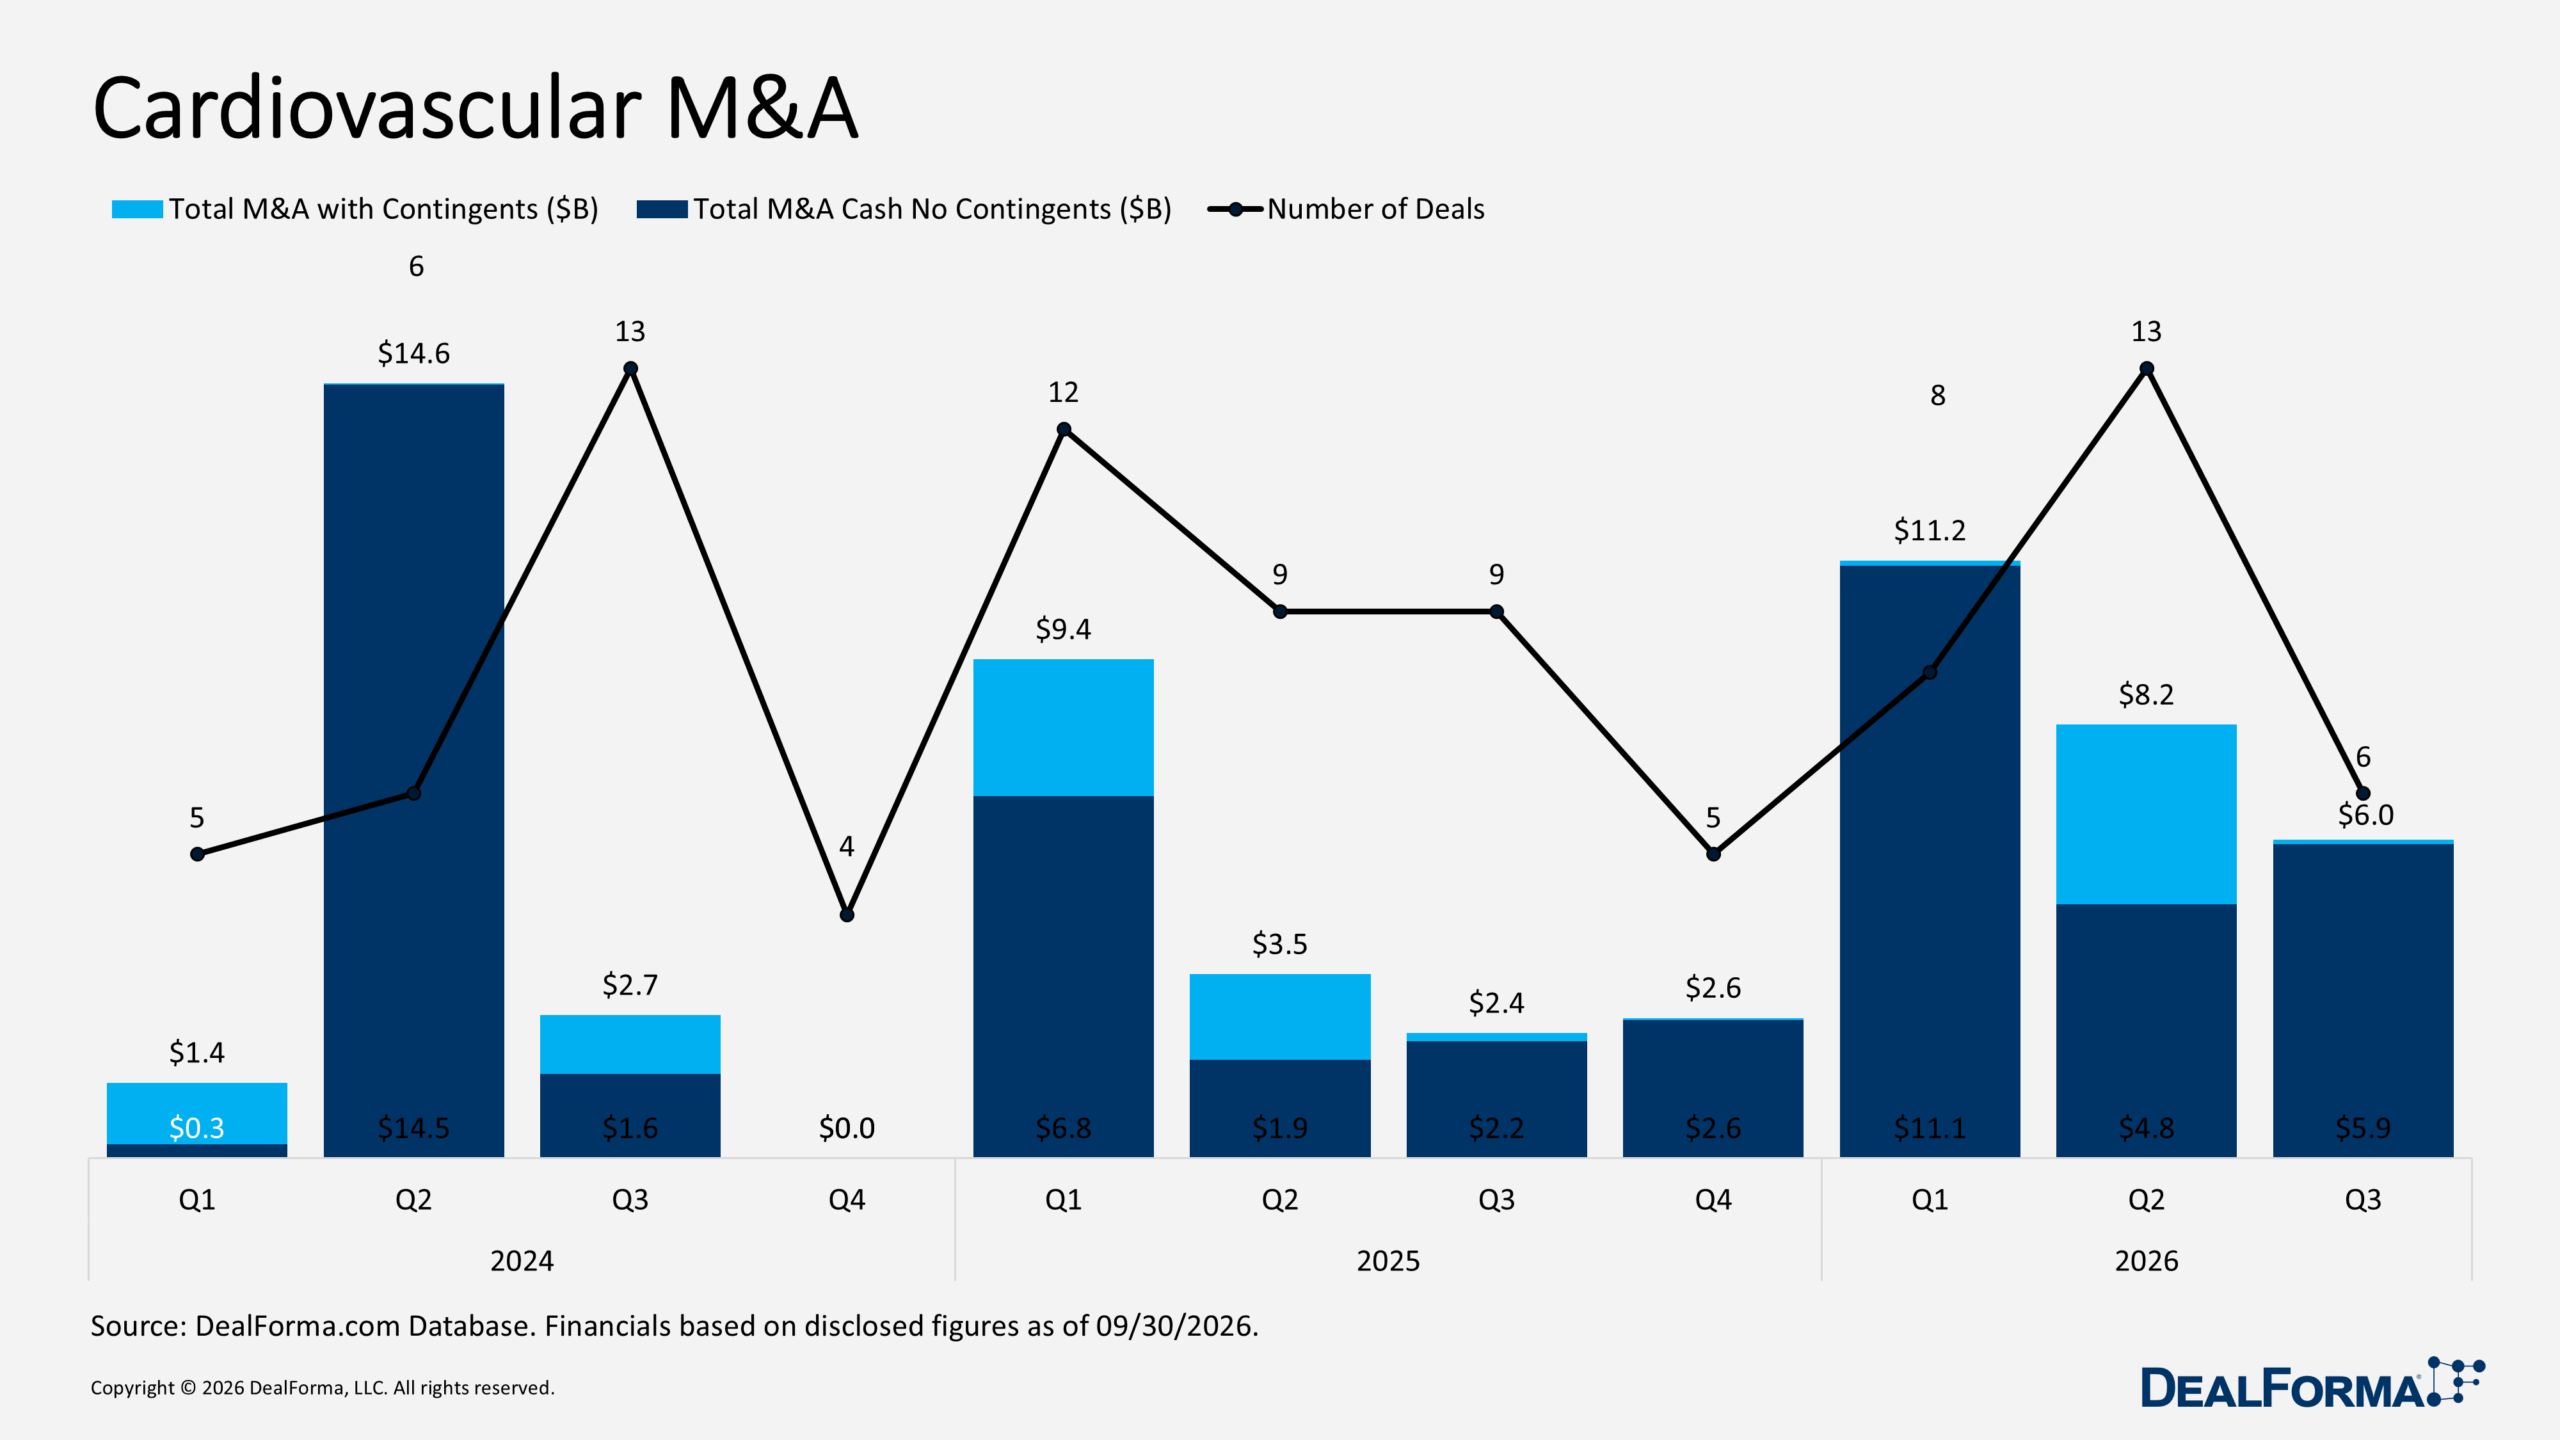
Cardiovascular M&A deal volume fell 54% quarter over quarter in Q3 2026, to 6 deals from 13 in Q2. Total M&A value, including contingents, declined 27% to $6.0B from $8.2B. Cash value excluding contingents, in contrast, rose 23% to $5.9B from $4.8B. Deal sizes increased significantly despite fewer transactions. Average upfront cash and equity climbed 271% to $3.0B from $796M, and the median rose 222% to $3.0B from $918M. Combined, Q2 and Q3 2026 produced 19 deals and $10.7B in cash value excluding contingents.
Prominent Cardiovascular M&As in Q3 2026
KKR acquiring Integer Holdings to take the company private – August 2026
KKR is taking Integer Holdings private at $127 per share in cash, for a total enterprise value of $5.7B. Announced in August 2026, the offer represents a 4.78% premium to Integer’s July 31, 2026, closing price. Integer is a CDMO serving medical device companies with design, manufacturing, and product development for Class III devices. Its portfolio spans capacitors, batteries, catheters, guidewires, introducers, medical coatings, medical textiles, and IPG components, among others. The company specializes in cardiovascular, neuromodulation, and cardiac rhythm management markets through its Greatbatch Medical and Lake Region Medical brands. The company expects to close at the end of 2026, after which Integer will delist from the New York Stock Exchange.
Medtronic option to acquire Pi-Cardia – September 2026
Medtronic secured an option to acquire Pi-Cardia for an estimated upfront price of up to $210M, plus potential earn-outs. Announced in September 2026, the deal also includes a Medtronic investment of up to $80M in Pi-Cardia. From 2027, Medtronic is expected to become the global distributor of Pi-Cardia’s ShortCut leaflet-modification device. Privately held medical device maker Pi-Cardia develops non-implant solutions, including a transfemoral catheter for aortic stenosis and other cardiovascular diseases.
Cardiovascular Venture Funding Activity
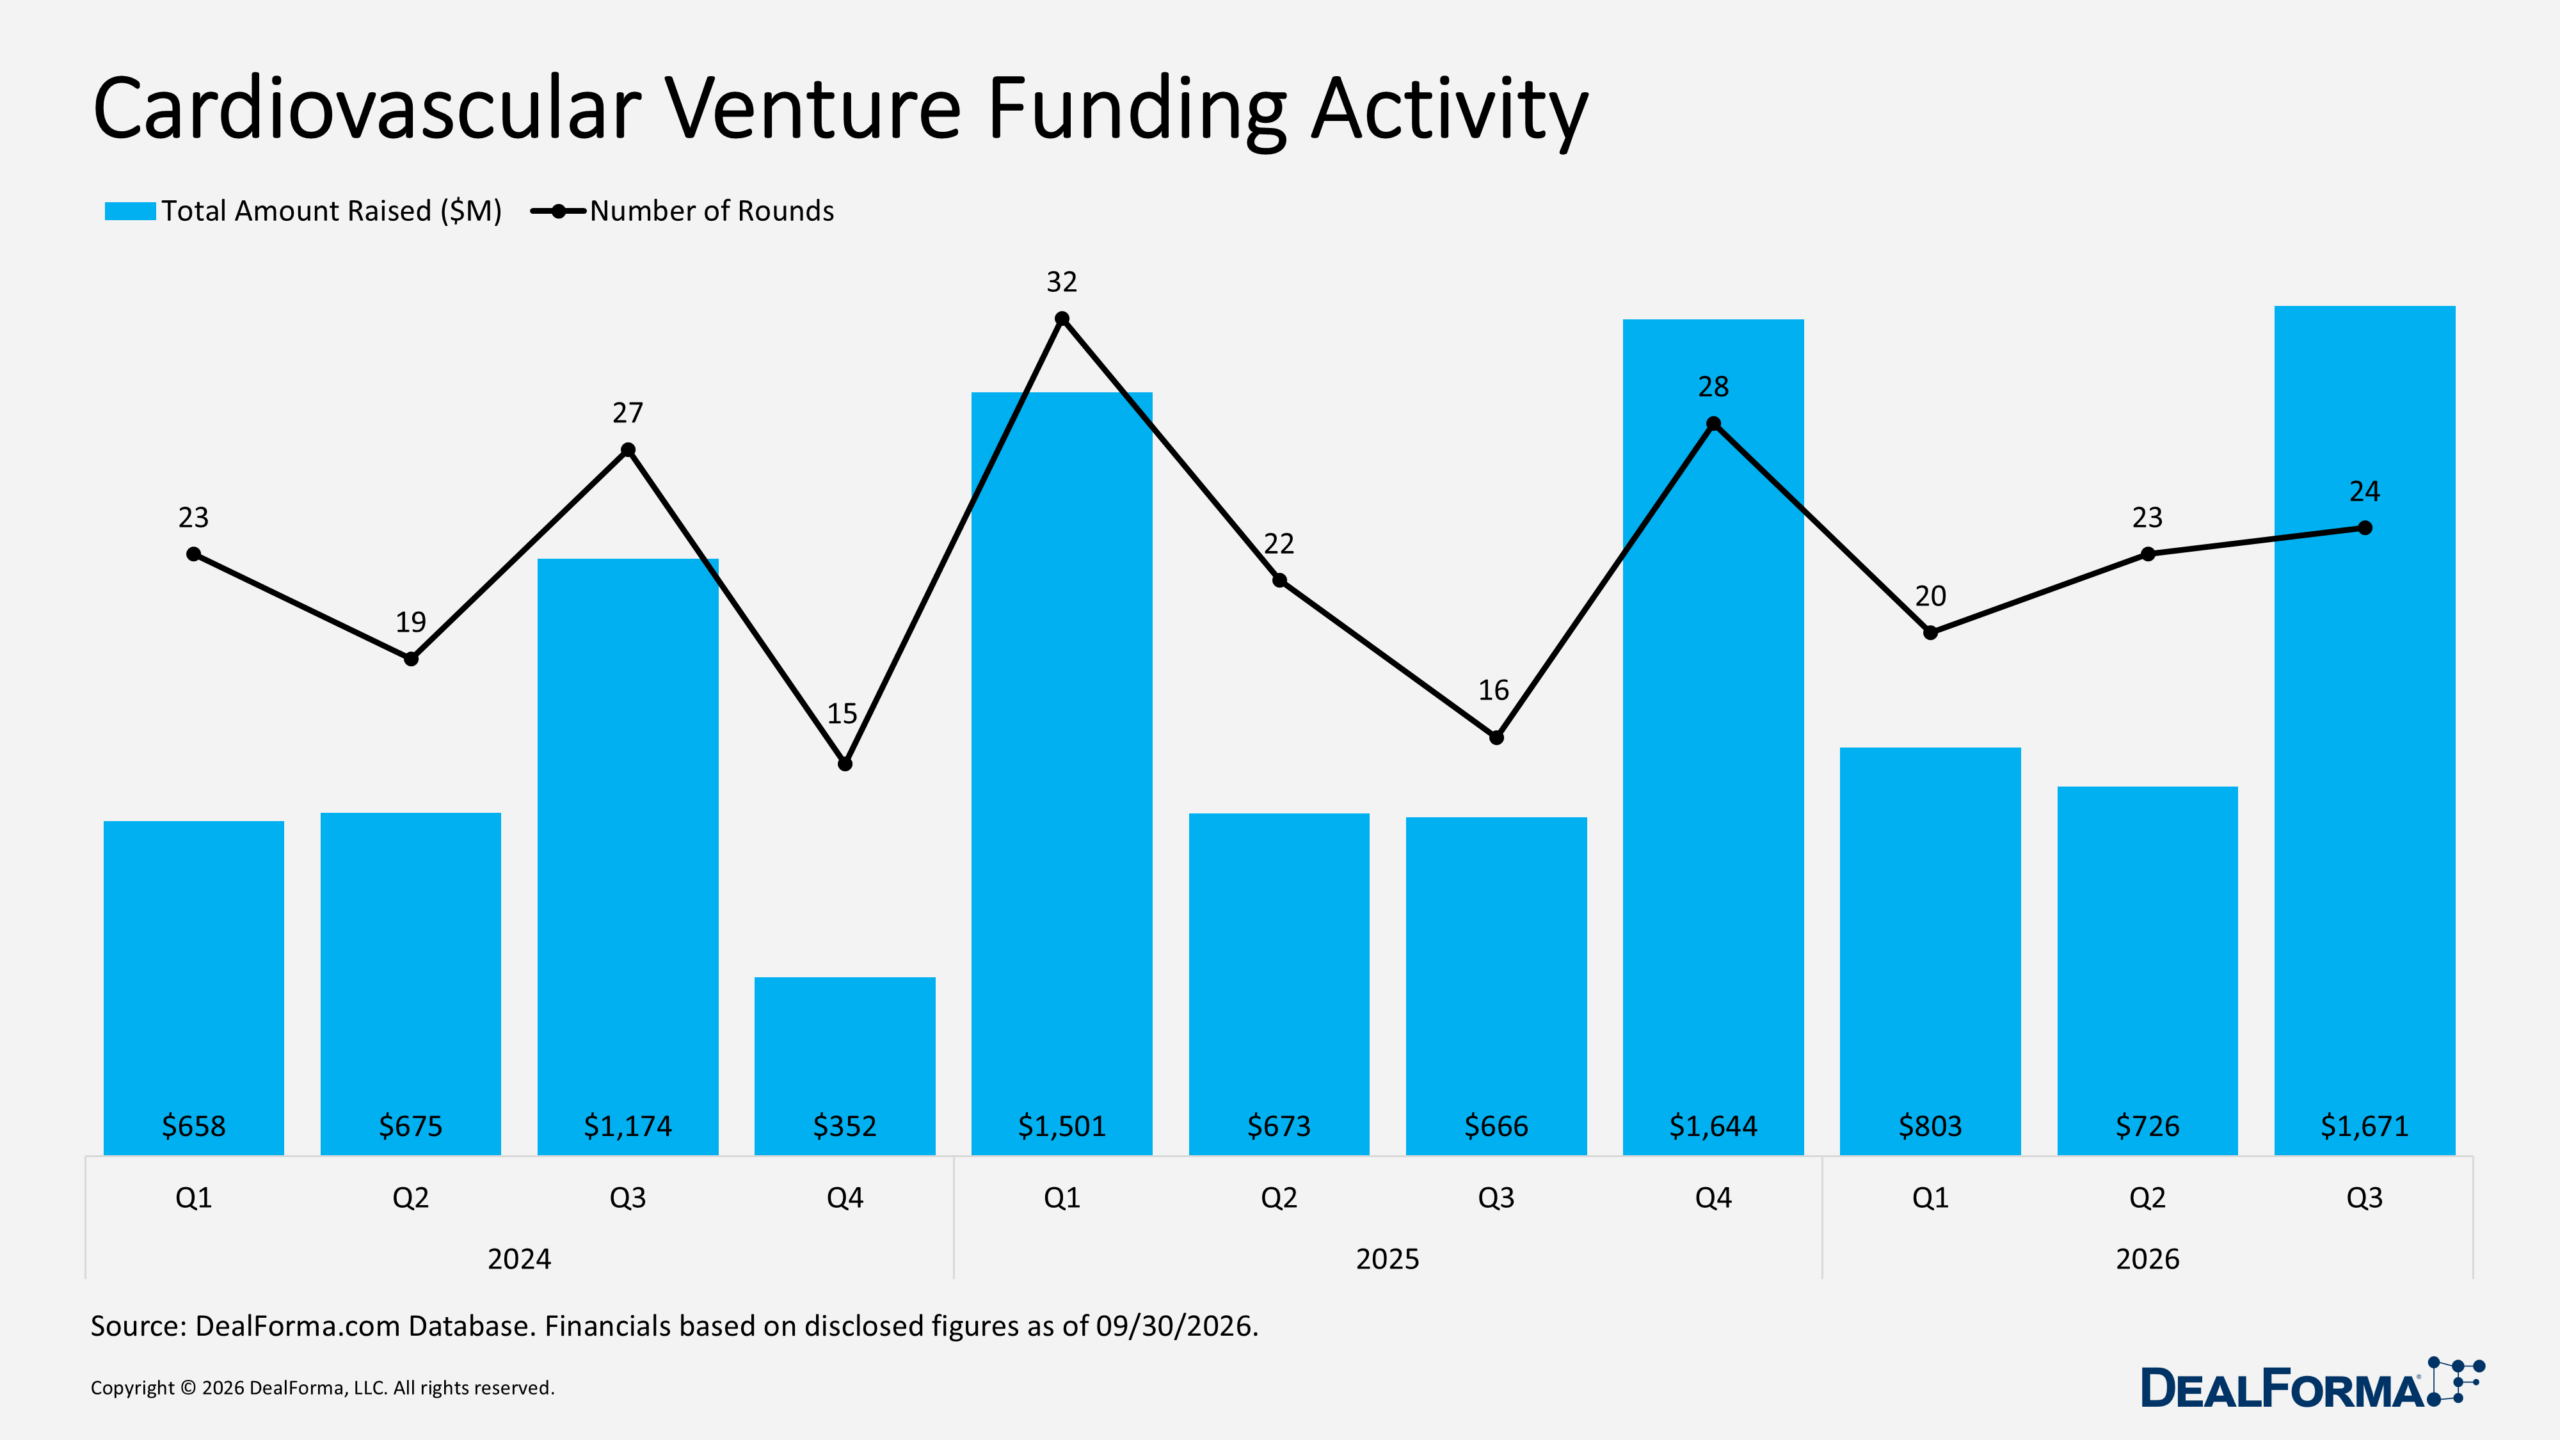
Cardiovascular venture funding activity strengthened in Q3 2026. Round volume edged up 4% quarter over quarter, to 24 funding rounds from 23 in Q2. Total capital raised surged 130% to $1.7B from $726M, showing stronger funding despite the modest rise in rounds. Combined, Q2 and Q3 2026 produced 47 funding rounds and $2.4B in total capital raised.
Prominent Cardiovascular Venture Funding Activity in Q3 2026
Neko Health – Series C – $700M – July 2026
Neko Health raised a $700M series C in July 2026, led by Lightspeed Venture Partners with O.G. Venture Partners co-leading. Atomico, General Catalyst, Lakestar, Liberty City Ventures, Positive Sum, and BDT & MSD also participated. Valuation was undisclosed; the round follows a $260M series B in January 2025. Its 60-minute, non-invasive scan uses proprietary sensors and blood analysis to screen for skin, metabolic, stroke, and heart attack risk. Over 100,000 members have been scanned, 350,000+ have registered, and 75% prepay their next scan. Proceeds fund R&D and US expansion, which began with a New York clinic in September 2026.
Function Health – Series Unspecified – $450M – July 2026
Function Health closed $450M in growth financing from General Catalyst’s Customer Value Fund (CVF) in July 2026. No series, valuation, or equity terms were disclosed. Per General Catalyst, CVF funds customer acquisition spend, repaid only by the cohorts acquired, up to a capped return. This funds growth without a new priced round, after a $298M series B at a $2.5B valuation in November 2025. The Austin-based company offers 160+ lab tests spanning heart, hormone, thyroid, liver, and kidney health from $365 per year. MRI and CT scans cost under $1,000 at 200+ US locations. The financing follows Function’s Q2 2026 acquisitions of Getlabs, an at-home blood-draw network, and SuppCo, a supplement platform.
Cardiovascular IPO Activity
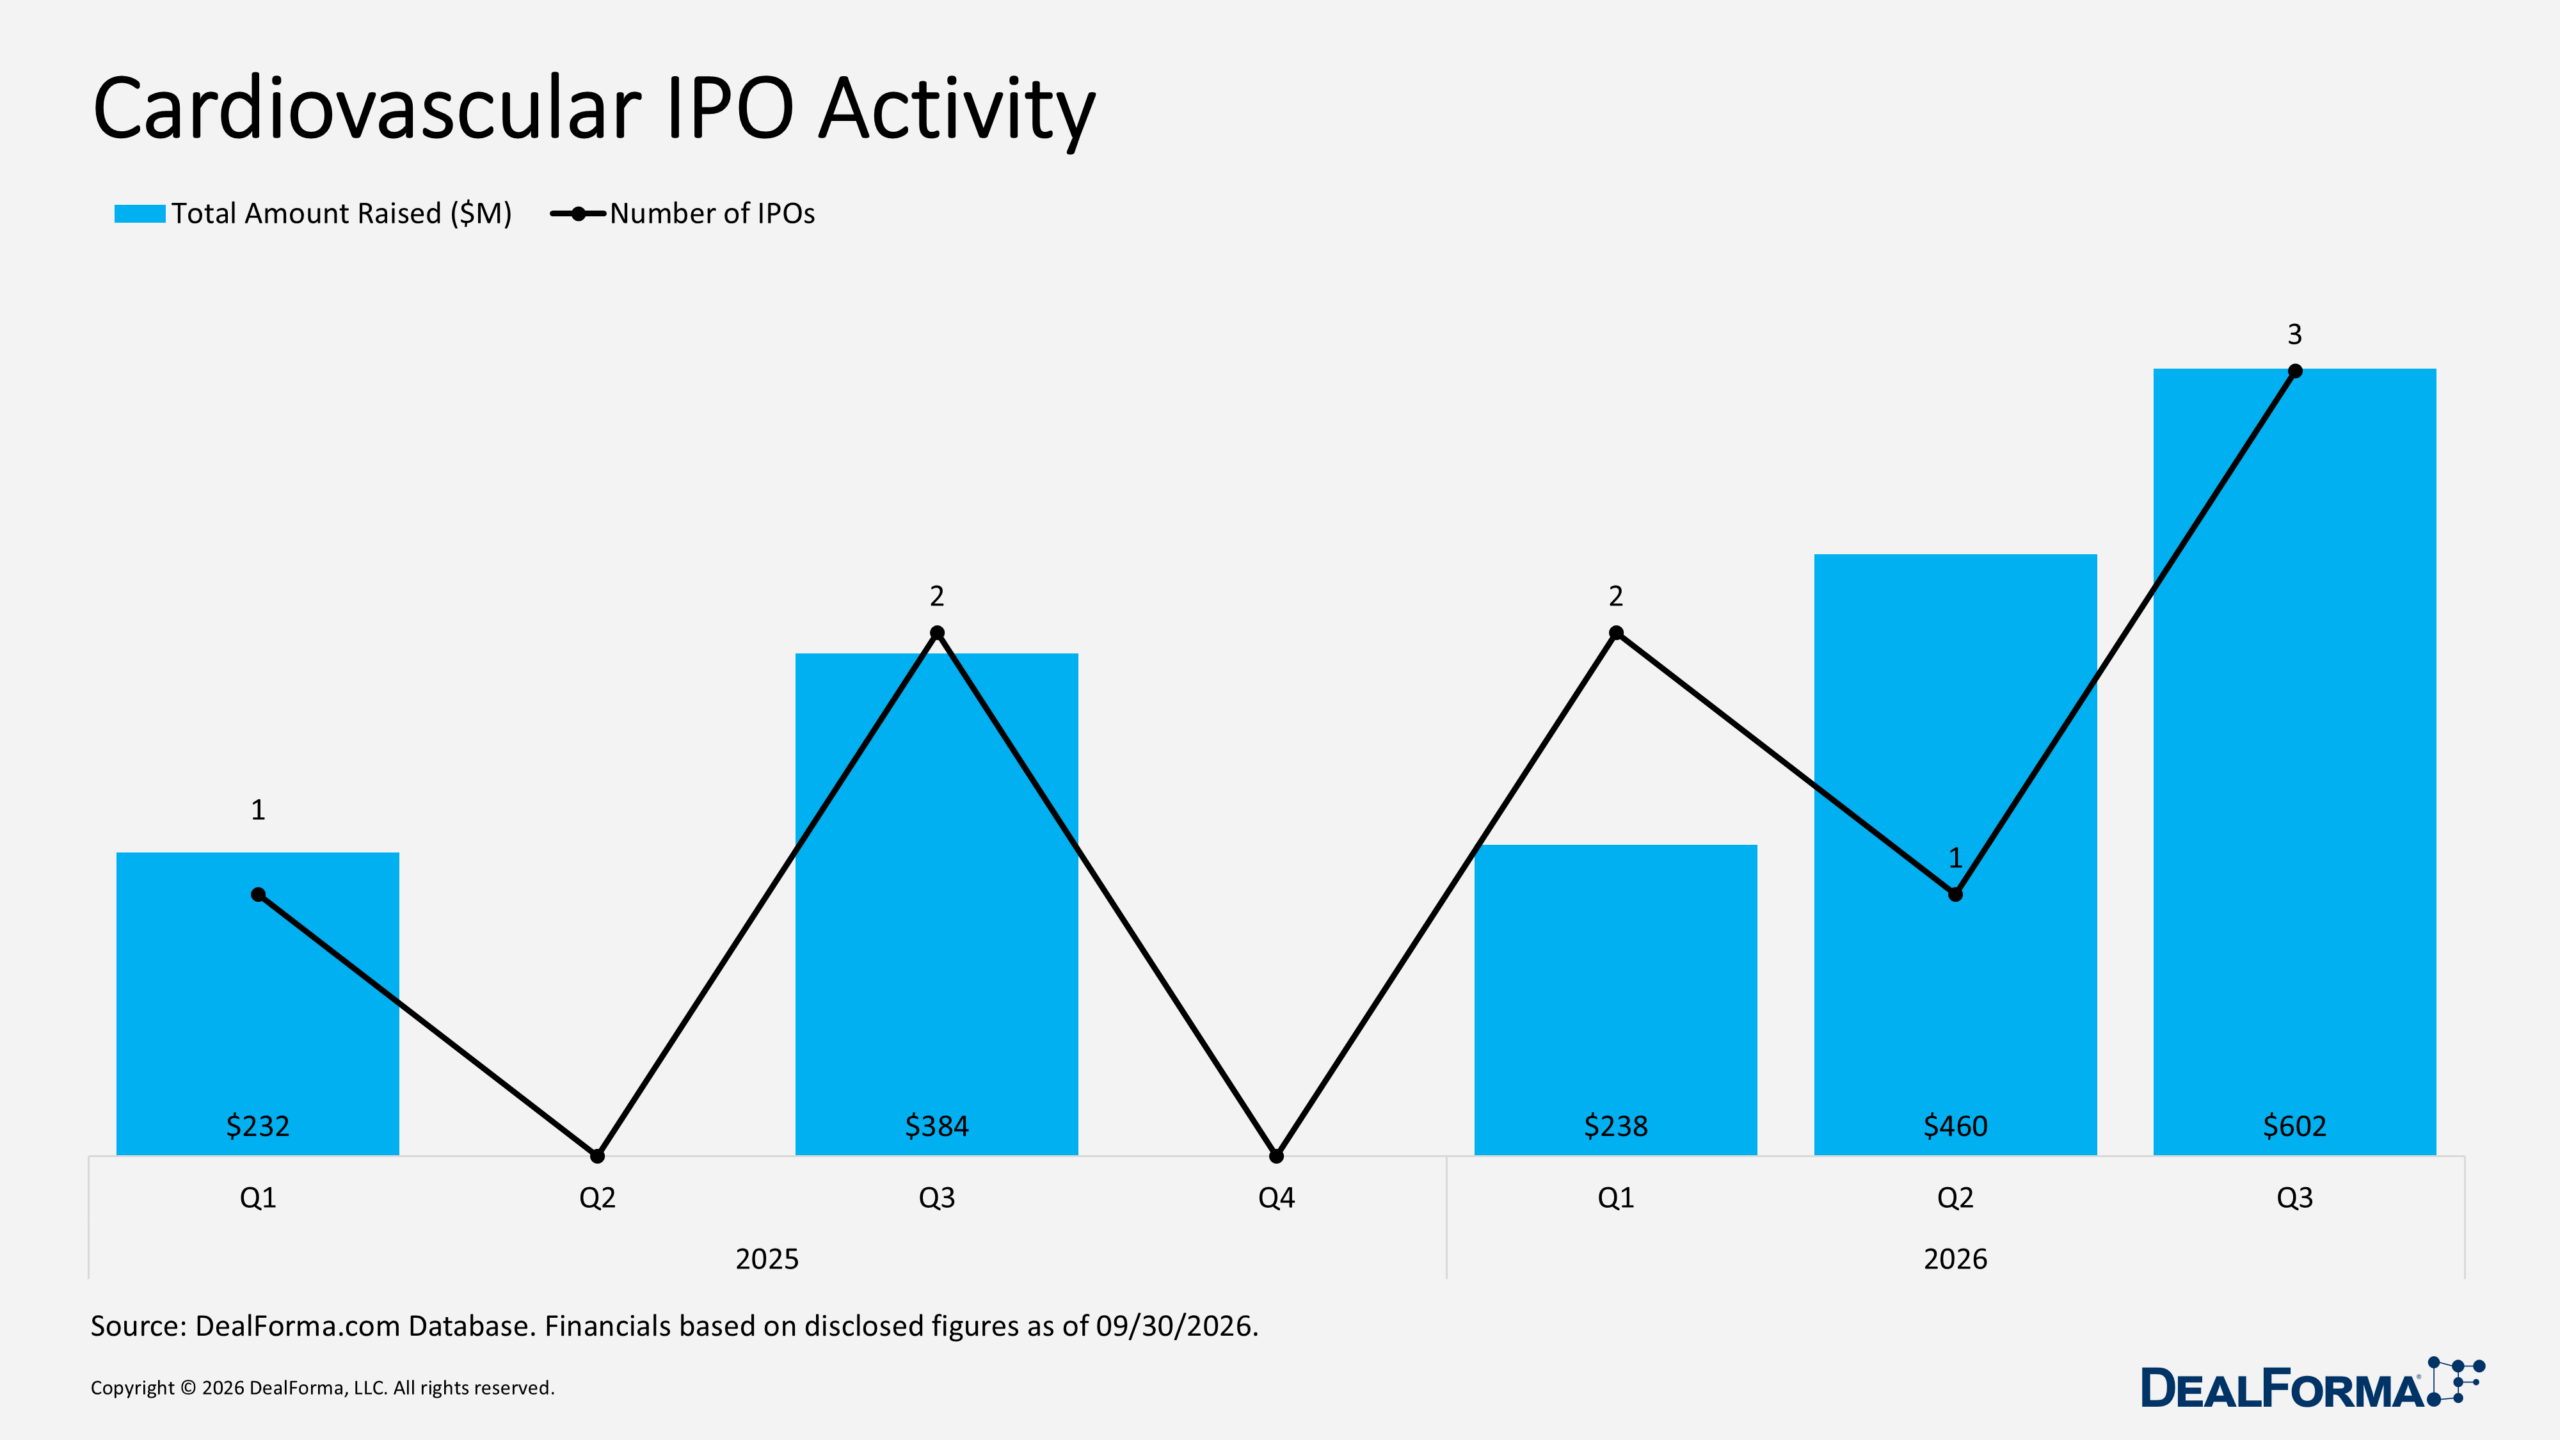
Cardiovascular IPO activity strengthened in Q3 2026. Offering volume rose 200% quarter over quarter, to 3 IPOs from 1 in Q2. Total capital raised grew 31% to $602M from $460M, reflecting momentum in public market activity. Combined, Q2 and Q3 2026 produced 4 IPOs and $1,062M in total capital raised.
Prominent Cardiovascular IPOs in Q3 2026
Braveheart Bio – IPO – $439.9M – August 2026
Braveheart Bio raised $440M gross in its upsized Nasdaq IPO in August 2026, netting about $405M. It sold 24,437,500 shares at $18.00, above the $15.00 to $17.00 range, including the full 3,187,500-share underwriters’ option. Lead asset BHB-1893 is an oral small-molecule cardiac myosin inhibitor for obstructive and non-obstructive hypertrophic cardiomyopathy (HCM). Braveheart in-licensed ex-Greater China rights from Jiangsu Hengrui in September 2025. In a 42-patient Phase 2 obstructive HCM study, one cohort hit an 86% complete gradient response at week 12. No treated patient’s ejection fraction fell below 50% during the 12-week core period. Proceeds fund global Phase 3 trials in both indications; the obstructive HCM trial has started. Interim topline data are due in H2 2027, with cash runway into 2029.
Scribe Therapeutics – IPO – $148M – July 2026
Scribe Therapeutics raised about $148M gross in its upsized Nasdaq IPO in July 2026. It sold 9,867,000 shares at $15.00, the top of its $13.00 to $15.00 range, including the full 1,287,000-share underwriters’ option. A concurrent $8M Sanofi private placement lifted aggregate gross proceeds to about $156M, or about $141M net. Lead candidate STX-1150 is an LNP-delivered CRISPR-CasX epigenetic silencer that represses PCSK9 to lower LDL-C without altering DNA. A first-in-human Phase 1 trial in Australia, in up to 64 adults, should report initial data in H1 2027. In non-human primates, one prototype dose cut LDL-C by more than 50% for two years. The investment case is durable LDL-C lowering that could replace chronic therapy for atherosclerotic cardiovascular disease. Sanofi and Eli Lilly are partners and shareholders.
Also check out Autoimmune R&D Partnerships, M&A, IPOs and Venture Funding – Q3 2026 Review